Building a Corporate Development Function
A corporate development function earns its place by helping the company allocate capital better and by delivering acquisitions the business can absorb. A busy pipeline and a closed deal are steps along the way. The real test is whether the company makes better strategic choices and gets the value it paid for.
This guide is a blueprint for a large company with several business leaders, established finance and legal teams, and competing demands for capital. Adapt the authority and meeting rhythm to your company. The templates are suggested management practices, not universal approval policies.
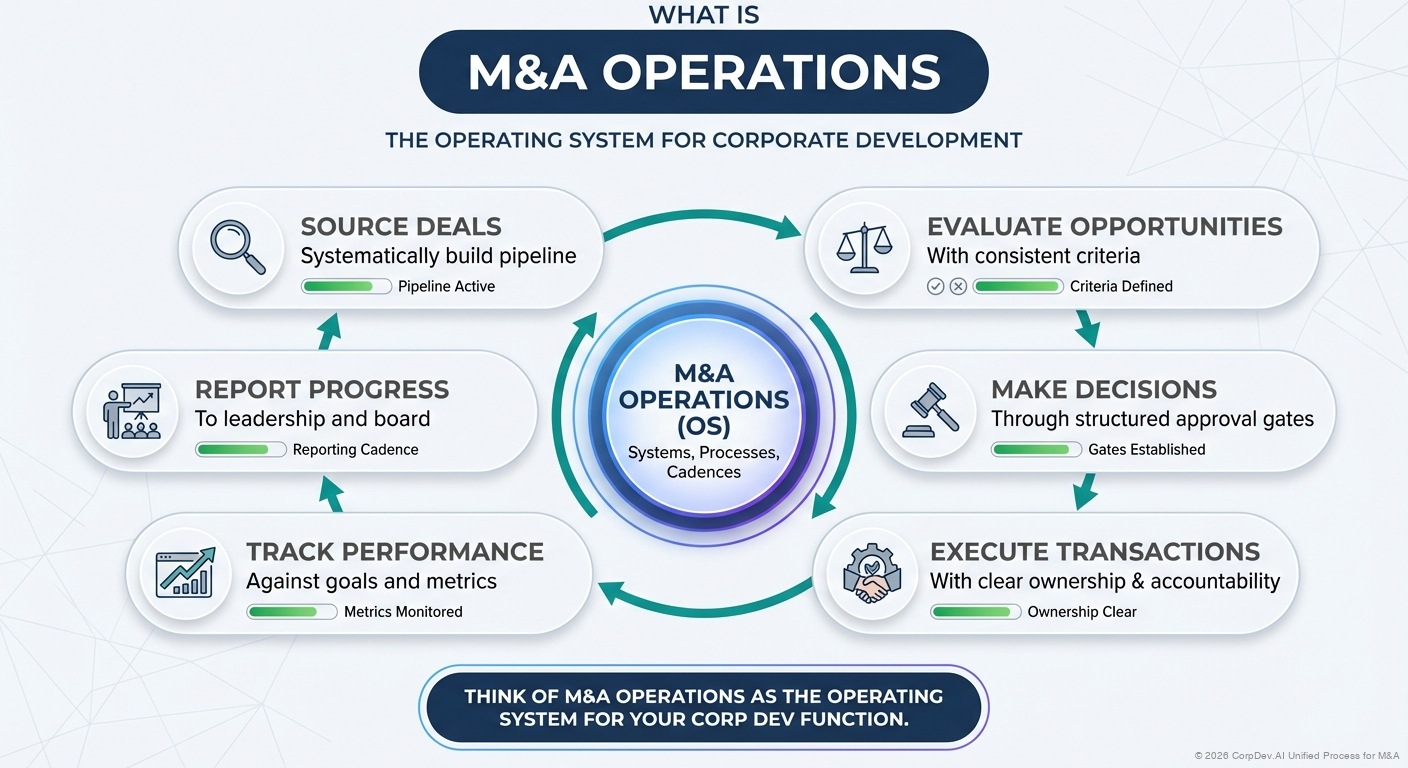 Source deals ↗Evaluate opportunities ↗Make decisions ↗Execute transactions ↗Track performance ↗Report progress ↗Build the operating system ↗Agree the function mandate ↗
Agree the mandate before hiring or outreach
Before hiring a large team or contacting any target, agree a short charter with the executive sponsor, CFO, general counsel, and business leaders. Settle the uncomfortable questions in writing. Who can start a deal? Who can stop one? Who commits resources? Who owns the business after closing?
A charter has eight fields. The right-hand column shows the evidence that each one is real rather than on paper.
| Charter field | Decision to document | Evidence the mandate is real |
|---|---|---|
| Strategic purpose | Which capabilities, markets, or portfolio changes should M&A deliver? | Named acquisition themes tied to the corporate plan |
| Scope | Acquisitions, divestitures, minority investments, partnerships, or ventures? | Deal types in scope, and explicit exclusions |
| Capital | How much capital can be considered, and what requires money to be moved from elsewhere? | CFO-owned funding assumptions, liquidity limits, and approval policy |
| Authority | Who approves exploration, indicative terms, binding commitments, and closing? | Delegation of authority agreed with legal and finance |
| Business sponsorship | Who owns the operating thesis and the post-closing result? | A named executive sponsor and receiving business leader |
| Functional commitments | What support will finance, legal, HR, technology, and operations provide? | Named leads, time allocated, and an escalation route |
| Success | How will the function be judged? | Decision quality, strategic outcomes, and results against the approved case |
| Review | When will the mandate be renewed or changed? | Annual strategy review, plus reconsideration when specific events occur |
Charter template: “Corporate development will pursue [themes] to achieve [strategic outcomes], across [deal types and regions]. [Executive] sponsors the program. [Business leader] owns the operating case and the integration outcome. Capital commitments follow [policy]. Early exploration is authorized within [budget and staff limit]. Exceptions require [approver], a recorded rationale, and a review date.”
The charter is incomplete if the team must source deals while business leaders can refuse diligence support indefinitely. Get an explicit agreement: a sponsor can reject a thesis, but an approved thesis gets the agreed resources and timely decisions.
Resolve disagreements before drafting the charter
Compare what executives expect from corporate development before writing the mandate. Identify conflicting priorities, decision rights, and resource commitments. Ask the relevant leaders to resolve those differences, then record the agreed owner and scope. A charter should reflect an explicit agreement rather than average incompatible requests.
Use the first 90 days to prove the process works
The goal for the first 90 days is a working investment process and a first view of the portfolio. Closing an acquisition is not a sensible 90-day goal for every company.
The table breaks the work into six blocks, each with a deliverable and a test of whether it is done.
| Period | Work | Deliverable | Done when |
|---|---|---|---|
| Days 1–15 | Interview leadership, business units, functional leads, and owners of past acquisitions | Draft mandate; history of prior deals and unresolved integration obligations | Leadership agrees what M&A should achieve and what has failed before |
| Days 16–30 | Turn strategy into acquisition themes; assess build, buy, partner, and divest alternatives | Theme briefs; portfolio gaps; first capacity assessment | Each theme has a sponsor, economic logic, exclusions, and known evidence gaps |
| Days 31–45 | Set authority, functional coverage, and information handling | Charter; decision calendar; staffing and budget request; information protocol | Legal, finance, and the receiving businesses accept their responsibilities |
| Days 46–60 | Build the target universe and screen a limited set against the mandate | Prioritized coverage map; target records; first screening memos | Every active opportunity has an owner, a next decision, and a credible reason to exist |
| Days 61–75 | Run a real investment review, or a retrospective of a past deal | Decision record; evidence register; model review; integration capacity check | The process produces a clear decision: advance, stop, hold, or rework |
| Days 76–90 | Review bottlenecks and set up ongoing reporting | Executive dashboard; next-quarter work plan; corrected operating procedures | Leaders can see capital at risk, resource constraints, and unresolved decisions |
Do not wait for a technology rollout to finish. Start with controlled records, named owners, and reliable permissions. Automate once the definitions and handoffs work.
Write down what each executive owns
CorpDev coordinates the investment process. It cannot check every technology assumption on its own, accept legal risk, or promise that the receiving business will deliver revenue synergies. Each executive owns a part:
- CEO or executive sponsor: portfolio direction, and settling conflicts between business units.
- CFO: financing capacity, fit with capital allocation, and the financial control framework. FP&A agrees how results will be measured after closing.
- Business sponsor: signs the operating thesis, confirms integration resources, and owns the acquired business's results.
- Head of corporate development: the deal recommendation, process quality, negotiation coordination, and the record of decisions and assumptions.
- General counsel: legal advice, approval formalities, information restrictions, regulatory strategy, and documents, with the right specialists.
- Functional leaders: sign off their findings and their commitments to fix problems. Silence is not acceptance.
- Integration leader: tests whether the plan can be delivered before binding approval, and coordinates Day 1 and the workstreams that follow.
For each significant disagreement, record the options, the consequences, the recommended resolution, and who is authorized to decide. A committee discussion that ends without a recorded outcome leaves the team exposed to contradictory instructions.
Size the team by workload, not company revenue
Size the function by the overlapping work, its complexity, and the specialist support available from other functions. Company revenue does not tell you how many cross-border carve-outs, integrations, or minority investments a team can handle.
Keep a rolling capacity plan showing each professional's committed time on sourcing, live deals, integration, portfolio monitoring, and running the function. Estimate demand separately for legal, finance, tax, HR, technology, and operations. Include vacations, recurring duties, and an explicit reserve for unplanned work.
Illustrative capacity calculation: Four professionals with 160 planning hours each per month provide 640 gross hours. Recurring management and sourcing take 240 hours, and the team reserves 80 hours for contingencies, leaving 320 hours for deal work. Two live processes needing 220 hours each create a 120-hour shortfall. These are planning assumptions, not productivity benchmarks; replace them with your observed workload.
Count a time saving from new tools in the plan only after timing real assignments from first draft to reviewed result, rework included.
Close a shortfall by resequencing work, cutting scope with explicit acceptance of the risk, borrowing qualified people, hiring, or adding advisers. Never close it by assuming every function can absorb the extra work. See team structure and compensation.
Budget the function separately from each deal
Keep the function's recurring costs apart from deal costs and integration investment. Otherwise each deal looks affordable while the shared team that delivers every deal goes unfunded.
| Budget | Include | Owner |
|---|---|---|
| Recurring function | Base pay, target bonus, equity expense, benefits, recruiting, data, systems, training, and travel | Head of CorpDev with finance and HR |
| Transaction | Legal, financial, commercial, technical, tax, regulatory, and other specialist diligence; financing and execution costs | Deal lead with finance |
| Integration | Dedicated resources, retention, systems, separation, transition services, restructuring, and change management | Receiving business and integration leader |
| Contingency | Identified downside scenarios, delayed closing, extended services, and remediation | Named budget owner under the approval policy |
Track incurred, committed, and forecast spending separately. A stopped deal still consumes resources. Record what was learned and why it stopped, and never let sunk cost become a reason to proceed.
Link every key assumption to its evidence
A good investment memo summarizes a controlled body of evidence; it cannot replace it. Keep one register of the assumptions that could change the decision. The example follows a single assumption from claim to approval.
| Field | Example: customer retention thesis |
|---|---|
| Assumption | The combined offering can retain the target’s largest customers |
| Evidence required | Contract-level revenue, renewal dates, change-of-control terms, customer interviews permitted by counsel |
| Owner | Commercial diligence lead |
| Confidence and gap | Management claim; contract and customer evidence pending |
| Economic consequence | Downside revenue and margin scenarios, including retention spending |
| Decision consequence | Reprice, require a condition, change integration scope, or stop |
| Outcome | Approved assumption, unresolved condition, mitigated risk, or rejected thesis |
| Approval record | Decision maker, date, evidence version, and remaining condition |
Use the same identifiers in diligence findings, the financial model, the committee paper, negotiation instructions, and integration initiatives. The goal is to trace any claim to its evidence and to the person accepting the risk. A company digital twin carries the same links into the operating model after closing.
Set information rules before first contact
Agree the protocol with counsel and information security before any outreach:
- NDA intake and permitted recipients
- Permissions for each target, restricted folders, and adviser access
- Retention, and how access ends
- Who can authorize customer contact or management interviews
Deals with competitors may need clean teams and limits on sharing competitively sensitive information. Counsel defines what may be exchanged and how each side must behave before closing. Integration planning does not authorize running the target before closing. Keep legal advice inside the privileged workflow rather than in a general issue tracker.
Apply the same rules to every research and drafting tool the team uses: the approved environment, access limits, retention settings, and how confidential information is handled. One named person owns that approval and corrects any record a wrong answer reached. Significant claims need a traceable source and a named reviewer, because a finished-looking analysis does not show that a diligence question has been answered.
End every governance meeting with a recorded decision
Four reviews cover most needs:
- A weekly team review for blocked decisions and capacity
- A regular sponsor review for pipeline priorities
- Scheduled investment committee slots, with a route for urgent decisions
- Periodic board reporting suited to the mandate
Match meeting frequency to the work. More meetings do not create better governance.
End each review with a recorded decision, owner, deadline, and the next evidence required. Send substantive papers early enough for challenge. Record dissent and the conditions attached to each approval. See approval gates and board reporting.
Keep the approved case after closing
Freeze the approved investment case and store later forecasts separately. Track the acquired business on its own, synergies, dis-synergies, integration costs, and cash received, without double counting. An initiative's annualized run rate is different from cash already received.
At agreed review points, compare actual results and the latest forecast with the original case, explain the variances, and assign corrective action. Keep the original thesis even if reporting lines or executives change. Finance checks the measurement basis; the business owner stays accountable for delivery.
Test the function after one quarter
At the end of the first quarter, leadership should be able to answer five questions:
- Which acquisition themes deserve capital, and which alternatives were rejected?
- Which opportunities were stopped, and what evidence changed the decision?
- Which live deals have unresolved assumptions or conditions?
- Which functional resources and integration commitments constrain the pipeline?
- What was promised on past deals, what has materialized, and who is taking corrective action?
If answering requires a scramble through personal inboxes and slide decks, strengthen records and ownership before adding deal volume.
Continue the work
© 2026 CorpDev.Ai Unified Process for M&A